If you are learning about options trading, you have probably come across the word Delta. It is one of the most important concepts in options because it helps traders understand how an option’s price may react when the price of the underlying asset changes.
At first, Delta can seem complicated. But once you understand the basic idea, it becomes much easier.
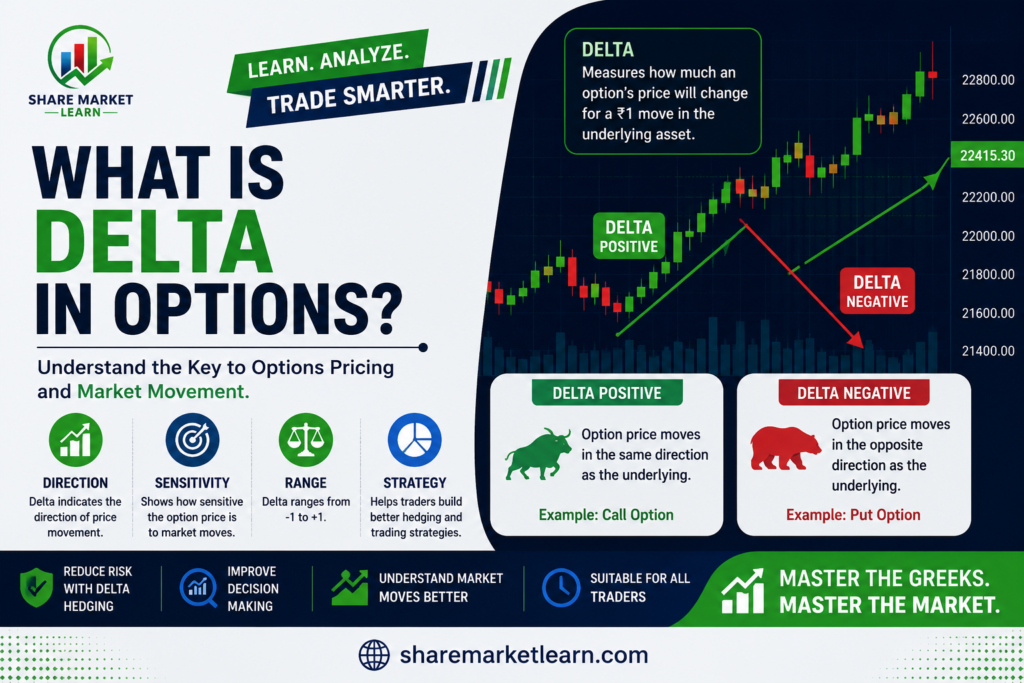
In simple terms, Delta tells you how much an option’s price is expected to change when the underlying asset moves by ₹1, assuming other factors remain unchanged.
Delta can also give traders an idea of how sensitive an option is to movements in the underlying asset.
In this guide, we will explain what Delta means, how it works for call and put options, how traders use it, and what beginners should know before using Delta in their options analysis.
Important: Options involve significant risk and are not suitable for every investor. The examples in this article are simplified for educational purposes.
What Is Delta in Options?
Delta is one of the Option Greeks.
The Greeks are measurements that help traders understand how an option’s theoretical price may respond to changes in different factors.
The major Greeks include:
- Delta – sensitivity to the underlying asset’s price
- Gamma – rate of change of Delta
- Theta – sensitivity to the passage of time
- Vega – sensitivity to implied volatility
- Rho – sensitivity to interest rates
Among these, Delta is often one of the first Greeks beginners learn.
For example, suppose a call option has a Delta of 0.50.
If the underlying stock increases by ₹1, the option’s theoretical price may increase by approximately ₹0.50, assuming other factors remain unchanged.
Similarly, if the stock falls by ₹1, the option’s theoretical price may decrease by approximately ₹0.50.
This is an approximation, not a guarantee.
What Does Delta Tell You?
Delta provides information about the relationship between the underlying asset and the option.
It can help answer questions such as:
- How sensitive is this option to price movements?
- How much might the option price change if the stock moves?
- Is the option deep in-the-money or out-of-the-money?
- How does the option behave compared with the underlying asset?
Delta is therefore useful for understanding the potential behavior of an option before entering a trade.
Delta for Call Options
For a standard call option, Delta is generally between 0 and +1.
For example:
- A call with Delta of 0.20 has relatively low sensitivity to the underlying asset.
- A call with Delta of 0.50 has moderate sensitivity.
- A call with Delta of 0.80 has relatively high sensitivity.
As a call option becomes deeper in-the-money, its Delta generally moves closer to +1.
As it becomes further out-of-the-money, its Delta generally moves closer to 0.
Example
Suppose a stock is trading at ₹1,000.
You purchase a call option with a Delta of 0.60.
If the stock rises by ₹10, the option’s theoretical price could increase by approximately:
₹10 × 0.60 = ₹6
Again, this is a simplified estimate. Actual option prices are affected by other factors, including time decay, volatility, and changes in Delta itself.
Delta for Put Options
Put options generally have negative Delta.
Their Delta typically ranges from 0 to -1.
For example:
- A put with Delta of -0.20 has relatively low sensitivity.
- A put with Delta of -0.50 has moderate sensitivity.
- A put with Delta of -0.80 has relatively high sensitivity.
The negative sign indicates that the put option generally moves in the opposite direction to the underlying asset.
Example
Suppose a put option has a Delta of -0.50.
If the underlying stock falls by ₹10, the option’s theoretical price may increase by approximately ₹5.
If the stock rises by ₹10, the put’s theoretical price may decrease by approximately ₹5.
This is why Delta is particularly useful for understanding the directional behavior of options.
Delta and Moneyness
Delta is also related to an option’s moneyness.
Moneyness describes whether an option is:
- In-the-money (ITM)
- At-the-money (ATM)
- Out-of-the-money (OTM)
Generally, for call options:
- Deep OTM calls tend to have lower Delta.
- ATM calls often have Delta around 0.50.
- Deep ITM calls tend to have Delta closer to 1.
For put options:
- Deep OTM puts tend to have Delta closer to 0.
- ATM puts often have Delta around -0.50.
- Deep ITM puts tend to have Delta closer to -1.
These are general relationships rather than fixed rules.
Delta as a Probability Estimate
You may sometimes hear traders say that Delta represents the probability of an option expiring in-the-money.
This can be a useful shortcut, but it is not exactly the same thing as probability.
For example, a call with Delta of 0.30 may sometimes be loosely described as having roughly a 30% chance of finishing in-the-money.
However, Delta is mathematically a sensitivity measure, while probability depends on the model and assumptions being used.
So beginners should avoid treating Delta as a guaranteed probability.
What Is Delta Hedging?
Delta can also be used for hedging.
Suppose an investor owns an option position with positive Delta.
They may use shares of the underlying asset to reduce the directional exposure of the position.
This is known as Delta hedging.
Professional traders and institutions may use Delta hedging as part of more advanced options strategies.
For beginners, the important idea is simply:
Delta helps measure directional exposure.
Delta-Neutral Positions
A position is sometimes described as Delta-neutral when its overall Delta is close to zero.
This means small movements in the underlying asset may have a relatively limited immediate effect on the total position, assuming other factors remain unchanged.
For example, a trader might combine options and the underlying asset in a way that offsets positive and negative Delta.
However, Delta is not fixed.
Because of Gamma, Delta can change as the underlying asset moves.
Therefore, a Delta-neutral position may not remain neutral for long.
Delta vs Gamma
Delta and Gamma are closely related, but they are not the same.
Delta tells you how much the option price may change when the underlying asset moves.
Gamma tells you how quickly Delta itself may change.
For example, imagine an option has a Delta of 0.50.
If the underlying asset rises, Gamma can cause the Delta to increase.
The option may then become more sensitive to additional price movements.
A simple way to remember them is:
Delta = Directional sensitivity
Gamma = Change in Delta
Why Is Delta Important for Beginners?
Delta can help beginners compare different options.
Imagine you are looking at two call options:
Call A: Delta = 0.30
Call B: Delta = 0.70
Call B will generally be more sensitive to changes in the underlying asset.
However, it may also have a higher premium and behave differently in terms of time decay and volatility.
This shows why selecting an option is not simply about finding the highest Delta.
Traders should consider the complete picture.
Common Mistakes Beginners Make With Delta
Mistake 1: Thinking Delta Is Fixed
Delta changes as the underlying asset price changes.
It can also change because of time remaining and other market variables.
Mistake 2: Treating Delta as Guaranteed Probability
Delta can sometimes be used as a rough probability-related reference, but it should not be treated as an exact probability.
Mistake 3: Ignoring Other Greeks
Delta is important, but it is only one Greek.
Theta, Gamma, Vega, and other factors can significantly affect an option’s price.
Mistake 4: Assuming Higher Delta Is Always Better
A higher Delta means greater sensitivity to the underlying asset. It does not automatically mean the option is better or more profitable.
The right option depends on the trader’s strategy, risk tolerance, market view, and objectives.
A Simple Delta Example
Let’s make the concept even easier.
Suppose a stock is trading at ₹500.
You are comparing two call options:
- Option A: Delta = 0.30
- Option B: Delta = 0.70
If the stock increases by ₹10, a simplified estimate would be:
Option A: ₹10 × 0.30 = approximately ₹3 increase
Option B: ₹10 × 0.70 = approximately ₹7 increase
Option B is more sensitive to the stock’s price movement.
But remember: these estimates can change because Delta itself changes and because other factors affect option prices.
Conclusion
Delta is one of the most important Option Greeks and is a valuable concept for anyone learning options trading.
It measures how sensitive an option’s theoretical price is to a change in the underlying asset.
For call options, Delta is generally positive and ranges from 0 to +1.
For put options, Delta is generally negative and ranges from 0 to -1.
Delta can also help traders understand directional exposure, compare different options, and build more advanced strategies such as Delta-neutral positions.
The easiest way to remember it is:
Delta = How much the option may respond to a ₹1 move in the underlying asset.
However, Delta should never be used alone. Option prices are also affected by time, volatility, interest rates, and other factors.
Once you understand Delta, learning the other Greeks—especially Gamma, Theta, and Vega—will give you a much stronger foundation for understanding how options work.
Frequently Asked Questions
What is Delta in options?
Delta measures how much an option’s theoretical price is expected to change for a ₹1 change in the underlying asset, assuming other factors remain unchanged.
What is a good Delta for an option?
There is no universally “good” Delta. Different Delta levels suit different strategies and risk profiles.
Why is call Delta positive?
Call options generally gain value when the underlying asset rises, so their Delta is positive.
Why is put Delta negative?
Put options generally gain value when the underlying asset falls, so their Delta is negative.
Does Delta change?
Yes. Delta is not fixed. It can change as the underlying asset price moves and as the option approaches expiration. Gamma measures the rate at which Delta changes.
Is Delta the probability of profit?
No. Delta is primarily a sensitivity measure. Although traders sometimes use it as a rough probability-related estimate, it should not be treated as an exact probability of profit or expiration in-the-money.
What is the difference between Delta and Gamma?
Delta measures an option’s sensitivity to the underlying asset’s price. Gamma measures how quickly that Delta changes when the underlying asset moves.